

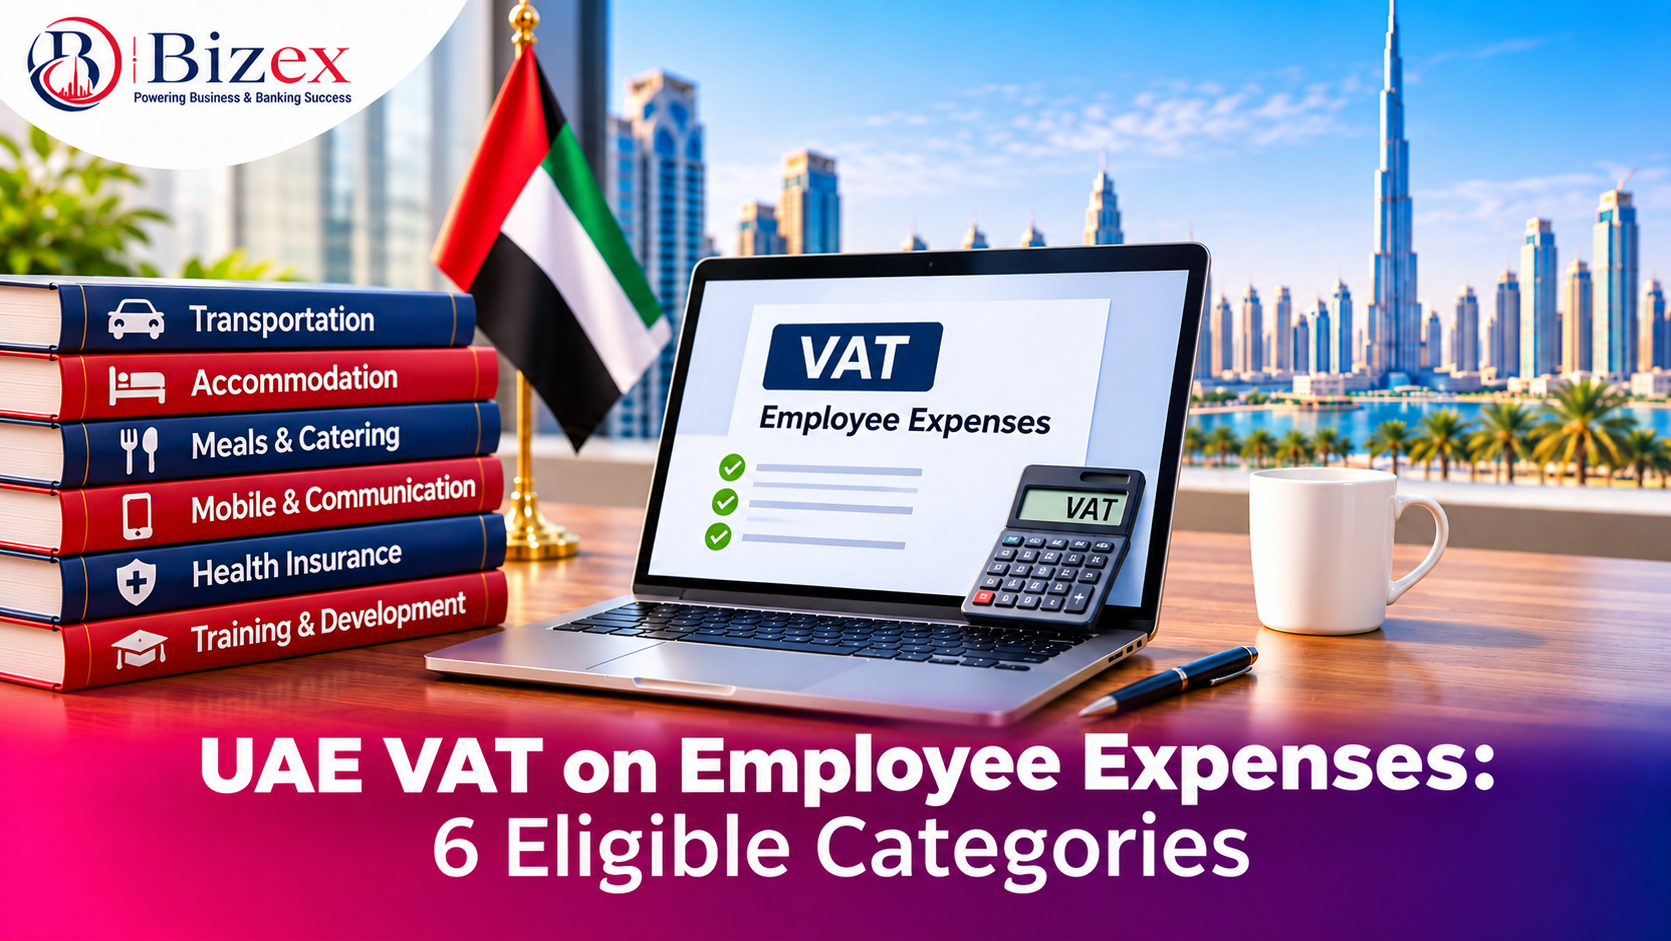
UAE VAT on Employee Expenses: 6 Eligible Categories

UAE VAT on Employee Expenses: 6 Categories Businesses Can Claim Input Tax On
Businesses operating in the UAE often incur expenses on employee transportation, accommodation, meals, mobile phones and other work-related services. While these expenses are necessary for daily operations, understanding whether the Value Added Tax (VAT) paid on them can be recovered is equally important for maintaining tax compliance.
The UAE Federal Tax Authority (FTA) has introduced Decision No. 17 of 2026, which clarifies the cases and conditions under which VAT-registered businesses can recover input tax on specific employee-related expenses. Effective from 1 October 2026, the decision identifies six categories of employee expenses that may qualify for input VAT recovery when the prescribed conditions are satisfied.
For businesses navigating these regulatory requirements, understanding VAT Services in Dubai can help them manage tax compliance, review eligible input tax claims, and maintain accurate financial records. However, companies cannot automatically claim VAT on every expense paid on behalf of employees. The expense must meet the relevant eligibility requirements and have a genuine connection to business operations.
What Are the New UAE VAT Rules for Employee Expenses?
The new UAE VAT rules explain when employers can recover input tax paid on certain goods and services provided to employees free of charge.Under FTA Decision No. 17 of 2026, businesses may recover input VAT on six specified categories of employee expenses, provided they meet the conditions applicable to each category.
The decision focuses on expenses that are necessary for business operations rather than benefits provided primarily for employees' personal enjoyment. Generally, the employer must demonstrate that providing the goods or services is required under a contractual obligation or a documented internal policy. Businesses must also satisfy the specific conditions for the relevant expense category and the wider UAE VAT input tax recovery requirements.
Six Employee Expenses Eligible for VAT Recovery in the UAE
The FTA decision covers six categories of employee expenses. Understanding each category's requirements can help businesses determine whether they qualify for input VAT recovery.
1. Employee Transportation Expenses
Businesses may recover input VAT on employee transportation services when the transportation is provided for specific work-related journeys. Eligible transportation may include travel between an employee's residence and workplace, journeys to client locations or travel to other places directly connected with job responsibilities.
However, the transportation must not be provided primarily for personal benefit. Employees must also not have the option to receive a cash allowance or other financial compensation instead of the transportation service. For example, a company arranging transportation for employees who work at a remote project site may qualify for input VAT recovery if all applicable conditions are met.
2. Food and Beverages Provided to Employees
VAT recovery may also be available on food and beverages supplied to employees in specific working conditions. This category mainly covers employees working or residing in remote, distant or isolated locations where suitable facilities for preparing meals or purchasing food and beverages are not reasonably available.
The provision of meals must be directly connected to the employee's working or residential requirements arising from the nature of the job. Employees must not have the option to receive cash compensation instead of the meals. For example, a company operating a project in an isolated location may provide meals to employees because nearby restaurants and food preparation facilities are unavailable. Ordinary daily meals or general employee refreshments should not automatically be treated as eligible expenses.
3. Work-Related Employee Accommodation
Some businesses need to provide accommodation because of the operational requirements of their activities.Under the new UAE VAT rules, input VAT on employee accommodation may be recoverable when the nature of the job requires employees to live near their workplace, project site or client premises.The accommodation must be provided for genuine operational reasons and should not form part of the employee's regular remuneration or personal employment benefits.
It must also meet the employee's basic living requirements and be proportionate to the nature of the work. Accommodation that includes unnecessary recreational or personal facilities may not satisfy the applicable conditions.For example, a construction company providing suitable accommodation to employees working at a distant project location may qualify for input VAT recovery if the relevant requirements are fulfilled.
4. Temporary Accommodation for New Employees
Businesses recruiting employees from other locations may need to arrange temporary accommodation while new employees settle into their jobs.The FTA decision allows input VAT recovery on qualifying temporary accommodation provided to newly recruited employees for a period not exceeding 30 days.
The accommodation must be appropriate to the employee's job requirements and basic living needs. For example, if a UAE company recruits an employee from overseas and provides temporary accommodation for 20 days while the employee arranges permanent housing, the related input VAT may qualify for recovery if all applicable conditions are satisfied. Businesses should maintain supporting documents showing the employee's recruitment date, accommodation period, and related expenses.
5. Mobile Phones, Data Packages and Internet Services
Mobile phones and internet connectivity are essential for employees who need to communicate with customers, colleagues and business partners.The new decision permits input VAT recovery on qualifying mobile phones, calls, data packages and internet services provided to employees for work-related purposes.
This also includes internet access at an employee's residence through a router or modem when it is necessary for performing job duties, including remote work and business communications outside regular working hours.The services must be used primarily for business purposes, although limited and incidental personal use is permitted.
Employers must establish a documented internal usage policy explaining permitted use and the consequences of unauthorised use. They must also maintain reasonable monitoring procedures and supporting records to demonstrate compliance.For example, a company providing mobile data packages to employees who regularly communicate with customers or work remotely may qualify for input VAT recovery when the relevant requirements are met.
6. Employee Parking Fees
Parking expenses may also qualify for input VAT recovery when they are incurred exclusively for business purposes.This can include parking fees paid by employees when attending external business meetings, visiting clients or travelling to locations directly connected with their work responsibilities.
Employers should maintain a documented internal policy explaining when parking expenses can be reimbursed and how employees should obtain approval. Supporting receipts should clearly show the parking date, time, amount paid, and VAT charged.For example, when an employee pays for parking while attending a client meeting and the company reimburses the expense under an approved business policy, the VAT may qualify for recovery if the applicable conditions are satisfied.
What Conditions Must Businesses Meet to Recover Input VAT?
Although the FTA decision identifies six eligible categories, businesses must satisfy the relevant requirements before claiming input VAT. Some important compliance considerations include:
➢ Business purpose: The expense must be directly connected to business operations and meet the conditions for its category.
➢ Contractual obligation or internal policy: The provision of eligible goods or services must be supported by the required employment arrangement or documented company policy.
➢ No cash alternative: Certain categories require that employees cannot choose cash allowances or financial compensation instead of the specified benefit.
➢ Proper documentation: Businesses should retain valid tax invoices, receipts, employment records, and supporting documents.
➢ Usage monitoring: For mobile phones and internet services, employers must establish usage policies and reasonable monitoring mechanisms.
➢ VAT eligibility: The business must satisfy the wider input VAT recovery requirements under UAE VAT legislation.
Companies should review their existing employee benefit arrangements to identify expenses that may qualify and update their internal procedures where necessary.
How Can Businesses Prepare for the New UAE VAT Requirements?
Preparing for the new employee expense VAT rules requires businesses to review how they manage employee benefits and related financial records. First, finance teams should identify employee-related expenses across all six categories. They should then examine employment contracts and internal policies to determine whether the arrangements meet the applicable requirements.Businesses should also establish clear procedures for approving employee reimbursements, collecting tax invoices, and recording business-related expenses.
For mobile phones and internet services, companies should introduce appropriate usage policies and monitoring procedures. Similarly, parking reimbursements should be supported by documented approval processes and receipts. Regular reviews of expense records and VAT returns can help businesses identify errors and maintain compliance with FTA requirements.
How Bizex Can Help Businesses with UAE Tax Compliance
Understanding UAE VAT regulations and maintaining accurate financial records are important for businesses operating in the country. Changes in tax requirements can also create additional responsibilities for business owners and finance teams.
Bizex LLC supports businesses with professional business setup and related corporate services in the UAE. Businesses looking to establish or expand their operations can explore the available support for company formation, licensing, and other business requirements.
Working with qualified tax professionals can also help businesses review employee expense arrangements, understand input VAT recovery conditions and maintain appropriate tax documentation.
Conclusion
The introduction of FTA Decision No. 17 of 2026 provides clearer guidance on recovering input VAT for six categories of employee expenses in the UAE. These include transportation, food and beverages, work-related accommodation, temporary accommodation for new employees, mobile phones and internet services, and parking fees.
However, VAT recovery is not automatic. Businesses must satisfy the specific conditions for each expense category, maintain proper documentation, and demonstrate that the expenses are connected to genuine business requirements.
By reviewing employee benefit policies, maintaining accurate financial records, and following the latest FTA requirements, UAE businesses can improve their VAT compliance and manage eligible employee expenses more effectively.
Frequently Asked Questions (FAQs)
1. Can businesses claim VAT on employee expenses in the UAE?
Yes. VAT-registered businesses may recover input VAT on six specified categories of employee expenses under FTA Decision No. 17 of 2026, provided the relevant eligibility conditions and general VAT recovery requirements are satisfied.
2. Which employee expenses are eligible for VAT recovery in the UAE?
The six categories include employee transportation, food and beverages in qualifying circumstances, work-related accommodation, temporary accommodation for new employees for up to 30 days, mobile phones and internet services, and business-related parking fees.
3. Can employers claim VAT on employee accommodation?
Yes. Employers may recover input VAT on qualifying work-related accommodation when it is required by operational needs, meets the employee's basic living requirements and satisfies the other conditions under the FTA decision.
4. Is VAT recoverable on employee mobile phones and internet services?
Yes. Input VAT may be recoverable when mobile phones, calls, data packages and internet services are necessary for employees' work duties and are used primarily for business purposes. Employers must maintain documented usage policies and reasonable monitoring procedures.
5. When did the new UAE employee expense VAT rules become effective?
FTA Decision No. 17 of 2026 became effective on 1 October 2026. It establishes the specific cases and conditions for recovering input VAT on qualifying employee-related expenses.